
 Linkedin

 Facebook
 Email
 more
This is a publication that is part of RSM’s Voice of SCM. On a monthly basis, RSM issues the Voice of Supply Chain Management (SCM). Our SCM consultants constantly follow global SCM developments and translate their impact into practical considerations for internationally active companies.
The EU Pay Transparency Directive requires employers to show that pay differences between women and men performing the same work or work of equal value rest on objective, gender-neutral criteria. Member States had to transpose Directive (EU) 2023/970 by 7 June 2026, and it combines transparency during recruitment, new information rights for workers, gender pay gap reporting and stronger enforcement.
Until now, pay has often been set locally, by country and legal entity, based on market benchmarks, collective agreements and individual negotiation. Although equal-pay legislation already applied, reporting obligations and individual information rights differed across Member States and workers often had limited visibility of how their pay compared. For employers with 150 or more workers, the Directive requires the first report by 7 June 2027, covering calendar-year 2026, while under the Dutch bill as currently proposed, the first Dutch report for this group would instead be due by 7 June 2028, based on calendar-year 2027 data. Nevertheless, businesses already need to build the foundation, because the pay structures and data behind a first report take longer to put in place than the time that remains.
This article was written by Isabelle Schollaardt (ischollaardt@rsmnl.nl) and Dick Brinkhof (dbrinkhof@rsmnl.nl). Isabelle and Dick are consultants with RSM Netherlands with a focus on Global Employment Services and Tax Governance.
What does the EU Pay Transparency Directive change?
The Directive strengthens enforcement of a principle that has been part of EU law for decades: equal pay for men and women for equal work or work of equal value. It makes pay structures more visible and gives employers greater responsibility for demonstrating compliance, reducing the reliance on individual workers to identify and challenge unequal pay.
Most attention goes to pay gap reporting, but three other elements are easily overlooked. During recruitment, candidates must receive information on the initial pay or its range, for example in the vacancy notice or before the interview and may not be asked about their pay history. During employment, workers may request information on their individual pay level and on the average pay levels, broken down by sex, for categories of workers performing the same work or work of equal value. Employers must inform workers annually of this right and of the steps required to exercise it and must make the criteria used to determine pay levels and pay progression easily accessible. Finally, workers may not be prevented from disclosing their pay to enforce equal pay, and Member States must prohibit contractual terms that restrict them from doing so.
The recruitment and individual information rights also apply to employers below the reporting thresholds. Member States may, however, exempt employers with fewer than 50 workers from making their pay-progression criteria available. Reporting applies from 100 workers, with employers of 150 or more going first. Employers must have pay structures that allow them to demonstrate that differences in pay between women and men performing the same work or work of equal value rest on objective, gender-neutral criteria.
What is the difference between equal work and work of equal value?
Equal work means the same or nearly the same job, which is what most employers already compare. Work of equal value extends to different roles that are comparable when assessed against objective, gender-neutral criteria. The Directive requires those criteria to include skills, effort, responsibility and working conditions. Their relevance and weighting may differ by role, and additional criteria may be used where relevant and justified. A warehouse supervisor and a customer service team lead may have little in common on paper yet be of equal value under these criteria. Without a documented, gender-neutral method for evaluating and classifying work, employers will struggle to identify which roles to compare and substantiate their pay structures.
The definition of pay covers basic salary and complementary or variable components received directly or indirectly in connection with employment, whether in cash or in kind. These include bonuses, allowances, overtime compensation and occupational pensions. In many organisations, differences arise in these additional components.
The Dutch implementation timetable
The Netherlands did not meet the 7 June 2026 implementation deadline. Under the Dutch bill currently before the House of Representatives (Wet implementatie Richtlijn loontransparantie mannen en vrouwen, 36 949), the government proposes that employers with 150 or more workers submit their first report by 7 June 2028, based on calendar-year 2027 data. This is one year later than required by the Directive. The Dutch Council of State advised that the Directive does not permit the first reporting obligation to be postponed in this way. The government nevertheless retained the proposed Dutch timeline, referring to the time needed to finalise the reporting rules, supporting software and monitoring arrangements, and is examining how the reporting information relating to 2026 can still be provided to the European Commission.
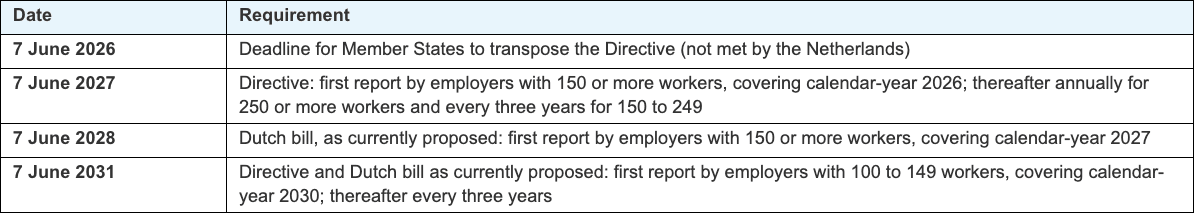
Even the Dutch start date is not settled. The government aims for entry into force on 1 January 2027, but the plenary debate in the House is only scheduled for 7 December 2026 and 11 January 2027, after which the Senate must still approve the bill. That date therefore appears unachievable, and it is not yet clear whether the first Dutch report would still cover calendar-year 2027. Draft secondary legislation was published for consultation from June 2026 onwards, followed by detailed proposals for the reporting methodology, template and data specification. For groups with entities in several Member States, implementation dates, thresholds and formats will differ per country, while the European standard behind them is the same.
The risks of waiting
A later reporting date does not remove the underlying equal-pay exposure. A worker who has suffered pay discrimination must be able to obtain full compensation, including back pay, related bonuses or payments in kind, compensation for lost opportunities and non-material damage, and interest, without a predetermined upper limit. National limitation periods for equal-pay claims may not be shorter than three years and must give workers an effective opportunity to bring a claim. Where an employer has failed to comply with its pay transparency obligations, the employer may be required to prove that no direct or indirect pay discrimination occurred. Member States may allow courts to disapply this rule where the employer demonstrates that the infringement was manifestly unintentional and minor. A joint pay assessment with workers’ representatives is required where the reported average pay level differs by at least 5% between women and men in a category of workers, the employer cannot justify that difference on the basis of objective, gender-neutral criteria, and the difference has not been remedied within six months of the report.
Following expiry of the implementation deadline, Dutch courts must interpret existing national law, as far as possible, consistently with the Directive. Certain sufficiently clear, precise and unconditional provisions may also be invoked against public authorities or qualifying public-sector bodies. The Directive does not, however, generally impose obligations directly on private employers without national implementing legislation. The equal-pay principle itself already binds private employers now, through Article 157 of the Treaty on the Functioning of the European Union (TFEU) and the Dutch Equal Treatment of Men and Women Act. A dry run on 2026 data is therefore not currently a statutory reporting duty in the Netherlands. We still regard it as sensible risk management, because it shows where pay data and the supporting explanations fall short before they are tested.
Organisations likely to face the greatest impact
- Employers with large variable pay components. The report must show the gap in complementary and variable components separately, as well as the share of women and men receiving them. The outcomes of bonus and commission schemes will therefore need to be traceable to documented, objective and gender-neutral criteria.
- Employers with distinct job families. Where technical and support roles, or production and office roles, sit in one organisation, the comparison of work of equal value across those families becomes central.
- Users of agency workers. They face additional data and coordination requirements. Under the Dutch bill, the hirer has reporting responsibilities in respect of workers made available to it, while the agency must provide the information needed for that reporting. The respective responsibilities should therefore be reflected in contractual data-sharing arrangements.
- Groups with central pay policies. They may face comparisons extending beyond a single legal employer where the relevant pay conditions can be attributed to a single source that establishes those conditions. This may be relevant where pay conditions are set centrally within a group, although a centrally designed group policy does not automatically establish that all workers across the group are comparable.
Groups headquartered outside the EU may fall within scope through their EU employers and operations, subject to the applicable national implementing rules and reporting thresholds. A global grading system designed at head-office level is not automatically gender-neutral within the meaning of the Directive.
What does pay transparency mean for tax governance and transfer pricing?
Pay transparency and tax governance controls
Pay transparency raises governance questions familiar to tax teams: how data and processes are controlled, what is disclosed and who takes responsibility at board level. Organisations with a Tax Control Framework can draw on its defined roles, documented controls, escalation procedures and formal sign-off when designing controls over pay data. Pay gap data will also become publicly accessible and comparable between employers. For the largest groups, it will sit alongside public country-by-country reporting. Boards should agree what the organisation will publish and how it will explain the results.
Reconciling payroll, HR and pay transparency data
The required data overlaps only partly with payroll tax data. To reduce the administrative burden, the Dutch government intends the reporting methodology to align as far as possible with existing definitions and data from the payroll tax return. Under the draft secondary rules, variable pay only counts where it is taxed as a special reward, and untaxed allowances under the work-related costs scheme are excluded. Errors in the payroll tax return therefore flow straight into the pay gap report, while items outside the report can still support an equal-pay claim.
The substantive EU concept of pay is nevertheless broader than, and does not fully align with, the data reported through the Dutch payroll tax return. It covers not only basic salary, but also complementary or variable components received directly or indirectly in connection with employment, which may include occupational pensions. In addition, the categories of workers performing the same work or work of equal value cannot be derived from payroll tax data. The precise data required for Dutch reporting will depend on the final implementing legislation and secondary rules. Employers should therefore build a documented reconciliation between payroll, HR and reporting data rather than assuming that the data sets match.
Transfer pricing implications of pay remediation
Finally, remedying an unjustified gap can involve back pay, compensation and interest. For entities remunerated on a cost-plus basis, back pay and related remediation costs raise a transfer pricing question: should they form part of the marked-up cost base, remain unmarked, or be allocated to another group entity? The answer should follow the functional and risk analysis, the cause of the cost and the relevant intercompany arrangements and should be addressed in the transfer pricing policy [LINK: transfer pricing policy, RSM Netherlands transfer pricing service page] before a claim arises. Back pay is generally taxed as wages when paid and may therefore also affect a later pay gap report. Compensation is in principle deductible for corporate income tax purposes; administrative fines are not.
Preparing for pay transparency
Preparation requires input from several functions. Four questions provide a practical starting point.
What do we pay and to whom?
Build one inventory for each relevant EU employer: headcount against the 100, 150 and 250 thresholds, job titles and grades, the applicable categories of workers and all relevant pay components, including variable pay, allowances, overtime, benefits in kind and relevant pension components. Record where each data point is held, who owns it, how it is validated and how it reconciles to payroll, HR and payroll tax reporting data.
Who is responsible?
Decide what sits with local HR, group reward, payroll, legal, tax and data privacy, who signs off in each country, and how workers’ representatives are involved. Where a Tax Control Framework exists, align roles and sign-off with it.
Where do obligations arise first, and how do we close the gaps?
Map, for each relevant Member State, the status of national implementation, the applicable thresholds, reporting frequency and reporting format. In the Netherlands, the published draft template can be used as a working basis, but systems should remain adaptable until the legislation and secondary rules are final. Then identify where a gender-neutral method of job evaluation is missing or job descriptions are out of date, and update vacancy texts, recruitment processes, pay-progression criteria and procedures for handling worker information requests.
How will we investigate and address pay differences?
Document the objective criteria for pay and pay progression, equip line managers to answer questions about pay, and agree how a reported difference of at least 5% between women and men within a category of workers would be investigated, objectively assessed and, where necessary, remedied. A dry run on 2026 data can show where the data, controls and supporting explanations fall short.
HR and reward, legal, finance and payroll, tax and the board all have a role in preparing for pay transparency. Their immediate priority should be a reliable view of jobs, pay components and headcount per entity. This will help the business meet existing equal-pay requirements and prepare for the new transparency and reporting obligations while the Dutch implementation date remains uncertain.
RSM is a thought leader in the field of supply chain management including ESG. We provide frequent insights through training and thought leadership, based on detailed knowledge of industry developments and practical application gained from working with our clients. RSM helps companies connect individual geopolitical and regulatory developments to the broader changes affecting their supply chains. By doing so, we support businesses in distinguishing short-term disruption from structural change and translating that assessment into coordinated decisions on sourcing, origin, landed cost, logistics and supply chain design. If you would like to discuss what these connected developments mean for your business, please contact one of our consultants.
