Linkedin

 Facebook
 Email
 more
Key takeaways:
The government is seeking to amend tax laws to introduce a 30% tax on discretionary trust income.
A three-year restructure window exists for those who wish to transfer assets out of discretionary trusts without triggering an immediate CGT liability.
Primary production income is excluded from the minimum tax rules, however complexity arises where a trust receives income from a combination of sources.
The 2026–27 Federal Budget introduced a number of potential legislative changes that are set to affect primary producers and the wider agribusiness sector.
One of the potential changes is a 30% tax on discretionary trust income, which was recently discussed in parliament when Treasurer Jim Chalmers introduced a bill seeking to amend the Income Tax Assessment Act 1997 and three other tax laws.
With trusts being a popular structure for farming businesses due to asset protection reasons and flexibility around ownership, succession planning and income allocation, the changes (if legislated) could have substantial implications.
Proposed new rules for discretionary trusts
The proposed reforms would introduce a minimum 30% tax rate on taxable income received into discretionary trusts from 1 July 2028. The tax would be paid at the trustee level, with individual beneficiaries receiving credits for the tax paid.
Prior to 2028, the government has offered a three-year restructure window from 1 July 2027 so people can transfer their assets out of discretionary trusts if they wish to. Transfers could be to a company or fixed trust and would not trigger an immediate capital gains tax liability.
For agricultural businesses, the most important detail is that primary production income is excluded from the minimum tax rules.


However, complexity arises where a trust receives a combination of income streams.
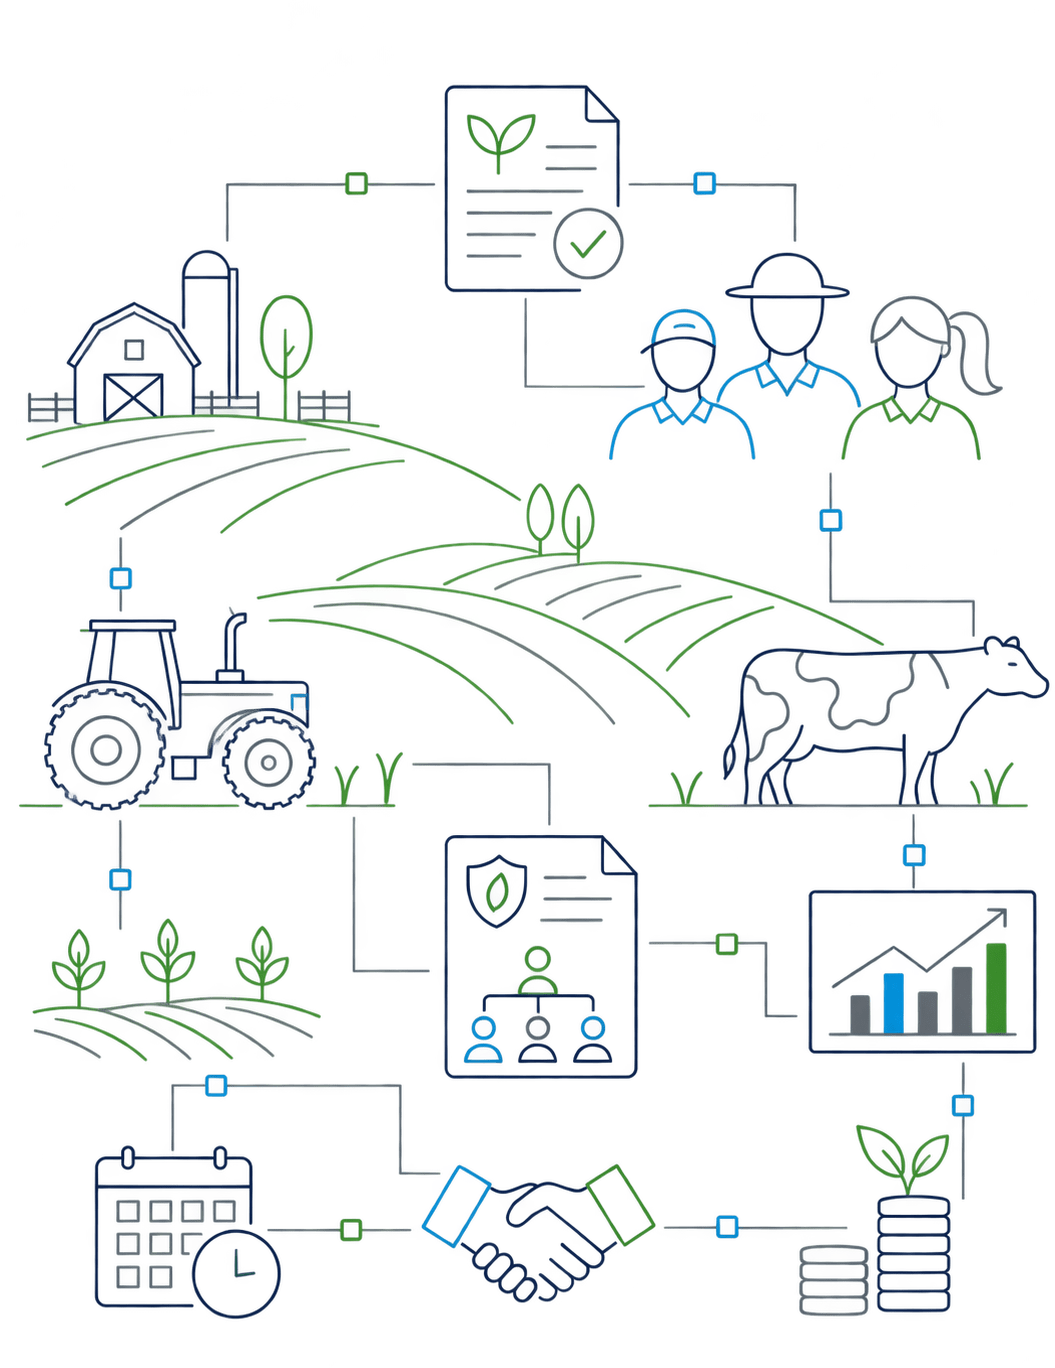
For example, a family trust may receive:
Cattle or grain income from primary production activities
Contracting income from providing services to other farms
Freight or machinery hire income
Income from renewable energy arrangements.
Where income is generated outside of primary production activities, trustees should consider if they want to keep directing all income into the one trust, or whether it makes sense to restructure.
How will trust changes impact succession planning and estate management for farmers?
Many family farms are multi-generational legacies and, for decades, discretionary trusts have sat at the centre of these legacies. The proposed 30% minimum tax changes this equation for farming families using discretionary trusts to distribute income from non-primary production activities.
For example, a farming family may distribute trust income between family members with varying levels of taxable income, such as a spouse working part-time or retired parents. Under the proposed changes, these distributions would no longer achieve the same tax outcome because the income would first be subject to a minimum 30% tax rate.
Many families also hold farmland or other assets in discretionary trusts as part of long-term ownership and succession plans. Where those assets sit outside the core farming operation and generate additional income, families will need to assess if the trust can still deliver the financial outcome they had planned for.
Also in need of review before the changes come into effect is any use of corporate beneficiaries within trusts. With the potential for trust income to be taxed at 30%, and then a further 25-30% company tax applied, corporate beneficiaries are looking at a double taxation event. If your current tax planning relies on corporate beneficiaries, you may want to reconsider this approach before 1 July 2028.
Differences for testamentary and unit trusts
Not all trusts will be treated the same under the new rules. Testamentary trusts and fixed trusts, including certain unit trust structures, will be treated differently to discretionary trusts.
For farming families, genuine testamentary trusts already in place at the time of the Budget announcement will generally retain their existing treatment. Income from assets held in eligible discretionary testamentary trusts existing at announcement is excluded from the new 30% minimum tax settings.
This means a succession plan that relies on an existing testamentary trust may continue as planned, provided the trust continues to meet the requirements. Families should be cautious about adding unrelated assets to these structures, as this may affect whether future income stays covered by the exemption.
Testamentary trusts created after the announcement will face additional requirements, including restrictions on who can benefit from the trust.
Planning tips for primary producers managing trusts under new tax guidelines
There is no single structure that will suit every farming business, and the right approach will always depend on the nature of the business, the type of assets owned, the risk associated, and the long term goals of those involved.
Looking ahead in light of potential trust reforms, primary producers may want to consider:

Mapping income streams
Identify which activities generate primary production income and which sit outside that category.

Reviewing entity structures
Consider whether current trusts and operating entities still reflect the way the business functions, and whether they will continue to provide value under the proposed rules.

Assessing restructure options
The Budget includes a three-year rollover relief period from 1 July 2027 to support eligible restructures.

Considering asset protection alongside tax outcomes
Combining activities into fewer entities may simplify administration, while separate structures provide other benefits. You will need to weigh the pros and cons of both.
How RSM can help
For some primary producers and farmers, the changes put forward in the 2026–27 Federal Budget will necessitate a deep dive into the way the business is structured and how it can best continue achieving its objectives in the future.
RSM’s experienced accountants and business advisers can help you make sense of how the proposed trust changes would apply to your farming business so you can make informed decisions moving forward.
To speak with an experienced adviser about how trust tax changes could impact your agribusiness, please contact your local RSM office.
We use your approximate location to show relevant local contacts. For more accuracy, may we access your device location?

Have a question?
Get in touch
Could proposed trust changes affect your farming business?
With potential changes to discretionary trust taxation on the horizon, now is the time to review your business structure and succession plans. RSM's agribusiness advisers can help you understand the potential implications and assess your options.
Complete the form below to speak with an RSM adviser.
Ideas and insights