Linkedin

 Facebook
 Email
 more

This article is part of our ongoing series looking at the impact of AASB 18 on financial reporting.
AASB 18 Presentation and Disclosure in Financial Statements (AASB 18) is effective for annual reporting periods beginning on or after 15 December 2026.
Our previous articles covered:
An overview of the requirements of AASB 18
Understanding Management-defined Performance Measures
In this article, we will consider in further detail the effect on the presentation and disclosure of financial statements.

AASB 18 updates to financial reporting
AASB 18 sets out new requirements designed to improve the structure and content of financial statements, as well as introducing new disclosures. It also clarifies the objective of financial statements: to faithfully represent the assets, liabilities, equity, income and expenses of an entity.
AASB 18 introduces explicitly defined roles for primary financial statements and the accompanying notes. Primary financial statements are structured summaries of an entity’s financial information that:
- Provide a clear overview of the entity’s recognised assets, liabilities, equity, income, expenses and cash flows.
- Enable comparisons between entities and between reporting periods for the same entity.
- Help readers identify items or areas where they would like more information from the notes.
The notes supplement the primary financial statements with material information on items.
The standard includes principles of aggregation and disaggregation for information on assets, liabilities, equity, income, expenses and cash flows to ensure that financial statements provide enough information to evaluate an entity’s ability to generate future net cash inflows and assess management oversight and use of economic resources.
Where do you need to provide information in financial statements?
Some information must be presented in the primary financial statements or notes to align with other AASB standards (for example disaggregation of revenue from contracts with customers).
Unless there are explicit aggregation or disaggregation requirements in another AASB standard, the principles of AASB 18 should be followed to determine where information is presented, taking into account:
Shared characteristics
- Aggregate items based on similarities and disaggregate them where differences exist.
Role clarity
- Align grouping with the distinct roles of primary financial statements and notes.
Transparency
- Ensure aggregation and disaggregation do not hide material information that could influence investor decisions.
If the information is material, disaggregate items to make that clear. If material information is not included in the primary statements, disclose that information in the accompanying notes.
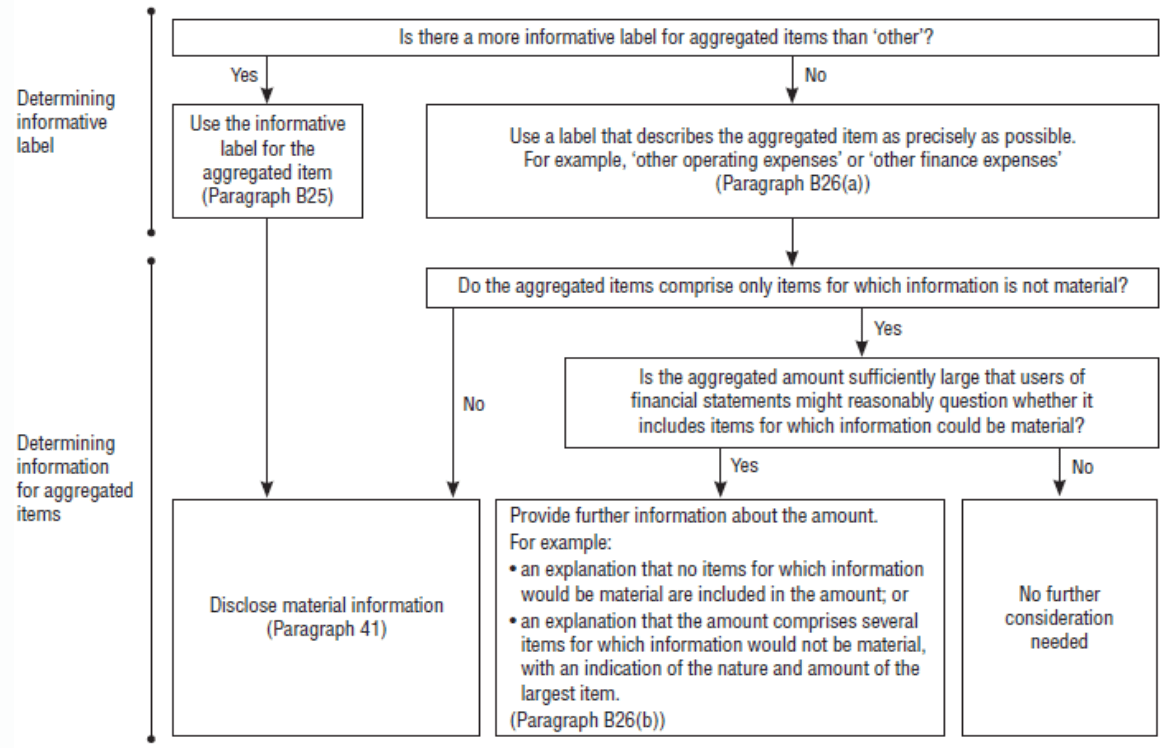
To help apply the principles, AASB 18 provides application guidance (B25-B26) on grouping items and labelling aggregated items, including which characteristics to consider when assessing whether items have similar or dissimilar characteristics:
What do you need to do to prepare for AASB 18?
To prepare for implementation, it is best to begin planning early. Key steps include:
- Develop a clear project plan and keep stakeholders informed throughout the process.
- Ensure your financial reporting team understands the changes to the aggregation and disaggregation principles, as well as the wider presentation requirements.
- Decide on clear and informative labels for aggregated and disaggregated information in your financial statements.
- If you are not an early-adopter, consider what disclosure you should include in respect of standards issued not yet adopted for your 31 December 2026 or 30 June 2027 financial report.
Planning now will help ensure a smooth transition to the new reporting standard.
Helping you navigate AASB 18
Please contact RSM Australia’s National Technical team if you would like further support or guidance in your preparation for the implementation of AASB 18.
Navigating AASB 18
AASB 18 represents one of the most significant changes to financial statement presentation in recent years. Stay ahead of the requirements with practical insights from our AASB 18 article series and support from our technical accounting specialists.
Need help preparing for AASB 18?
Our team can help you understand the impact, manage implementation and ensure your financial reporting remains compliant.
Navigating AASB 18
AASB 18 represents one of the most significant changes to financial statement presentation in recent years. Stay ahead of the requirements with practical insights from our AASB 18 article series and support from our technical accounting specialists.
Need help preparing for AASB 18?
Our team can help you understand the impact, manage implementation and ensure your financial reporting remains compliant.
Ideas and insights